Singapore's Evolving Role in Regional Supply Chain Finance
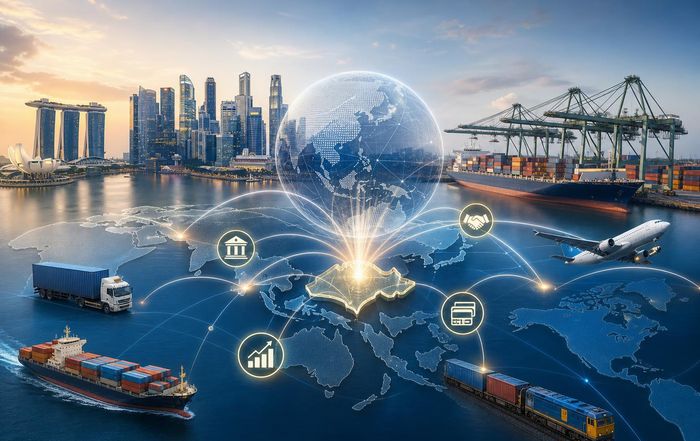
Singapore has spent three decades building itself into a trade and financial hub for Asia. Today, its next frontier is supply chain finance: the web of instruments, platforms, and institutions that ensure working capital flows as smoothly as physical goods. As global manufacturers diversify production across Southeast Asia, and as cross-border trade becomes more fragmented and regulated, the city-state is positioning itself as the region's coordination point for liquidity, risk management, and digital trade infrastructure. Join as we examine how Singapore's regulatory framework, banking sector, technology ecosystem, and regional connectivity are shaping its role in supply chain finance, and what this means for corporates, financiers, and investors across Asia.
Why supply chain finance matters to Singapore's position in Asia
Supply chain finance (SCF) sits at the intersection of trade, credit, and technology. It covers structures such as payables finance (reverse factoring), receivables discounting, inventory finance, and purchase order funding, often supported by digital platforms that connect buyers, suppliers, financiers, and logistics providers. For export-oriented economies, SCF is not a niche product set but an enabler of trade growth and resilience.
Singapore's economy is deeply exposed to regional trade flows. The city-state is one of the world's largest trans-shipment hubs, a major commodities trading center, and a key base for multinational treasuries. According to the Monetary Authority of Singapore (MAS), trade-related activities and financial services are central pillars of its GDP. As production networks shift from a China-centric model to a "China+1" or "Asia-plus" configuration involving Vietnam, Thailand, Indonesia, India, and others, demand is rising for cross-border financing structures that can deal with multi-jurisdictional risk, complex logistics, and different legal systems.
This is precisely where Singapore has comparative advantages: a concentration of global and regional banks, a sophisticated legal and dispute resolution framework, proximity to fast-growing ASEAN markets, and an active public-sector push into digital trade infrastructure. For banks and corporates, Singapore increasingly functions as a regional command center for trade finance and banking, even when production and consumption occur elsewhere in Asia.
Regulatory and policy foundations: MAS as a regional anchor
A key reason global institutions base their Asian trade and SCF businesses in Singapore is the regulatory environment. MAS has long promoted trade finance as part of Singapore's broader financial sector development. It offers a relatively predictable supervisory regime, clear capital and risk-management rules, and strong alignment with international standards such as Basel III and the recommendations of the Financial Stability Board at https://www.fsb.org/.
In supply chain finance, this matters because regulators globally have scrutinized the treatment of SCF exposures after high-profile corporate failures elsewhere exposed opaque off-balance sheet liabilities. MAS has pushed for improved disclosure, risk classification, and data reporting without discouraging legitimate SCF structures. This balanced stance appeals to global banks and institutional investors who need regulatory clarity to scale programs across borders.
Beyond prudential rules, Singapore's government has embedded trade and SCF into its broader economic strategy. Enterprise Singapore, accessible at https://www.enterprisesg.gov.sg/, co-funds or supports trade digitalization projects that include financing components, particularly for small and mid-sized enterprises (SMEs) that struggle to access credit directly. Initiatives like the Networked Trade Platform and various trade single-window efforts are designed to reduce paperwork and create data rails that financiers can use to assess risk and automate decisions.
For international readers, this policy framework means SCF solutions designed or booked out of Singapore are more likely to be aligned with global risk, compliance, and transparency expectations. That is particularly relevant for institutional investors and corporates who want to tap Asia's growth without taking on opaque legal or regulatory risk.
Banking, capital markets, and the concentration of trade expertise
Singapore's role in regional supply chain finance is also a function of its banking and capital markets depth. Major global banks such as HSBC, Standard Chartered, Citi, and BNP Paribas run significant Asian trade finance operations from the city-state, while local institutions like DBS, OCBC, and UOB have grown from domestic players into regional champions. These banks offer end-to-end trade and SCF solutions that span documentary trade, open account finance, and structured commodity transactions.
From a corporate perspective, this concentration of expertise allows multinational buyers to structure regional payables finance programs anchored in Singapore that extend out to suppliers in Vietnam, Malaysia, Thailand, India, or China. The anchor buyer's credit is typically booked in Singapore, while suppliers in other jurisdictions receive early payment in their local currency from participating banks. The city-state's role as a regional treasury hub-supported by favorable tax treatment and sophisticated cash-management products-reinforces this centralization.
Capital markets add another layer. Singapore's bond and securitization markets, overseen by Singapore Exchange, have been used for trade receivables securitizations and asset-backed programs that recycle SCF exposures into capital-market instruments. This allows banks and non-bank platforms to free up balance sheet capacity and scale financing to mid-tier suppliers. While the market is still smaller than in Europe or the United States, the combination of legal certainty, investor familiarity, and regional trade flows positions Singapore as a natural Asian hub for trade-linked capital-market issuance.
For investors and treasury teams, these capabilities connect closely with broader investment and business strategies: Singapore offers access to trade-linked assets, risk-sharing structures, and multi-currency solutions that sit at the heart of regional supply chains.
Digital trade infrastructure and the push toward data-driven finance
Where Singapore has been particularly active is in digital trade infrastructure, which underpins the next generation of supply chain finance. The government and industry have backed a series of projects aimed at moving from paper-heavy, document-based processes to data-centric, interoperable systems.
One pillar has been the adoption and promotion of the Model Law on Electronic Transferable Records (MLETR) developed by the United Nations Commission on International Trade Law (UNCITRAL), which can be explored at https://uncitral.un.org/. By recognizing electronic bills of lading and other transferable documents as legally equivalent to paper, Singapore is enabling financiers to rely on digital trade documents with clear legal standing. This is critical for inventory finance, receivables finance, and collateralization of goods in transit.
Another pillar is cross-border data connectivity. MAS and other agencies have championed initiatives such as the TradeTrust framework, which aims to ensure that electronic trade documents are interoperable and verifiable across different platforms and jurisdictions. While the underlying technical work is often invisible to end-users, the result is a more reliable flow of trade data that banks and alternative financiers can use to price risk, detect fraud, and automate disbursements.
These efforts intersect naturally with Singapore's broader ambitions in technology and innovation. The city-state has supported fintech experimentation through regulatory sandboxes and grants, and MAS maintains a strong public stance on responsible innovation at https://www.mas.gov.sg/. The upshot is a growing ecosystem of trade and SCF fintechs-ranging from digital trade documentation providers to alternative lending platforms-that often base their Asian headquarters in Singapore to leverage regulatory clarity and access to bank partners.
For corporates and SMEs across Asia, this digital infrastructure can translate into faster onboarding, better visibility on invoice status, and more competitive financing options that are embedded into logistics and procurement systems rather than bolted on as an afterthought.
Serving ASEAN and "China+1": Singapore as a coordination hub
The geographic logic of Singapore's SCF role is straightforward. ASEAN is one of the world's fastest-growing regions, with a combined population exceeding 650 million and increasing integration through the Association of Southeast Asian Nations (ASEAN), which maintains an official portal at https://asean.org/. Production networks are spreading across Vietnam, Indonesia, Thailand, and the Philippines, while Singapore functions as a high-value services and coordination node.
In practice, many global manufacturers and consumer brands use Singapore as the base for their regional procurement, treasury, and risk management teams. Supply chain finance programs are often designed and governed from the city-state, even when the underlying trade flows involve factories and suppliers elsewhere. This allows anchor buyers to standardize terms, documentation, and risk criteria while tailoring execution to local conditions.
For example, a Singapore-based regional headquarters might negotiate a payables finance program with a group of international and local banks that covers suppliers in multiple ASEAN countries. The program can be structured in Singapore law, with standardized documentation and clear dispute resolution mechanisms, while individual suppliers interface with local bank branches or digital platforms in their domestic markets. Singapore's role is not to replace local banking systems but to orchestrate them around a common framework.
This orchestration is particularly valuable as companies adopt "China+1" strategies. With production diversified across China, Vietnam, Malaysia, India, and beyond, working capital management becomes more complex. Singapore offers a central vantage point from which to monitor exposures, aggregate data, and ensure consistent risk treatment across jurisdictions. For firms concerned about geopolitical risk or supply chain fragmentation, this centralization of financial control can be as important as physical diversification of manufacturing.
Integrating SMEs into regional supply chains
A recurring challenge in supply chain finance is inclusion. Large multinational buyers and tier-one suppliers typically enjoy good access to credit, while smaller suppliers-especially in emerging markets-face higher costs and more stringent collateral requirements. If left unaddressed, this can undermine the resilience of regional supply chains and limit the development impact of trade.
Singapore has sought to position itself as a conduit for more inclusive finance into the broader region. Enterprise Singapore and private-sector partners have launched initiatives to help SMEs digitalize their trade flows, adopt e-invoicing, and participate in SCF programs anchored by larger buyers. MAS has also worked with international organizations such as the Asian Development Bank (ADB), reachable at https://www.adb.org/, and the World Bank Group, at https://www.worldbank.org/, which regularly highlight the global trade finance gap and the need for risk-sharing mechanisms to support smaller firms.
In many cases, Singapore-based banks and fintechs are building regional platforms that allow SMEs in neighboring countries to upload invoices, track payment status, and access early payment based on the credit of their large customers. These platforms often integrate logistics data, customs declarations, or purchase order information to strengthen risk assessment-a natural extension of Singapore's trade digitalization agenda.
For SMEs, this approach can reduce reliance on informal lenders, lower financing costs, and smooth cash flow volatility linked to long payment terms. For buyers and investors, it improves supply chain stability and offers exposure to a broader base of suppliers without dramatically increasing operational complexity.
Risk management, regulation, and the legacy of scandals
Singapore's ambitions in supply chain finance have not been without setbacks. The collapse of several commodity-trading and trade-finance-heavy firms in recent years, including cases involving fraud and mis-representation of collateral, exposed weaknesses in traditional, document-based trade finance and raised questions about risk controls in some parts of the market. Global regulators, including MAS and the Bank for International Settlements (BIS) at https://www.bis.org/, have since emphasized the need for better transparency and data in SCF and trade finance.
In response, Singapore's authorities and industry groups have tightened standards around collateral verification, know-your-customer (KYC) procedures, and credit underwriting. Banks have become more cautious about highly leveraged commodity trades and opaque structures, while investing in analytics and third-party data services that can verify shipment and inventory information.
From a regional perspective, these episodes have arguably strengthened Singapore's long-term position. They have accelerated the shift toward more data-driven, platform-based SCF, encouraged greater collaboration between banks and fintechs, and underscored the value of legal reforms such as MLETR adoption. For corporates, there is now greater emphasis on transparent, programmatic SCF structures rather than ad-hoc, relationship-driven facilities with limited oversight.
At the same time, stricter standards can make it harder for riskier or smaller players to obtain financing. This is where risk-sharing mechanisms with multilateral institutions, export credit agencies, and development banks-many of which maintain regional offices in Singapore-become important. They can help crowd in private capital to support suppliers and sectors that might otherwise be underserved.
The role of technology, AI, and data in the next phase
Looking ahead, Singapore's role in regional supply chain finance is likely to be defined as much by data and algorithms as by traditional banking relationships. The city-state is actively promoting responsible artificial intelligence in financial services, and MAS has issued guidelines on the use of AI and data analytics in areas such as credit scoring and fraud detection. These guidelines sit alongside broader AI governance work by international bodies like the Organisation for Economic Co-operation and Development (OECD), which maintains resources at https://www.oecd.org/.
In SCF, AI and advanced analytics can be used to analyze invoice patterns, detect anomalies, forecast default risk, and optimize dynamic discounting terms. When combined with real-time logistics and customs data, they allow financiers to move from static, one-off credit assessments to continuous, behavior-based risk monitoring. Singapore's concentration of banks, fintechs, data providers, and regulators in a compact ecosystem makes it an attractive testbed for such innovations.
Digital identity and e-KYC solutions are another area of focus. Projects that link corporate registries, trade platforms, and banking systems can simplify onboarding for SMEs and reduce fraud risk. The success of these initiatives will influence how far SCF can penetrate into the long tail of regional suppliers.
For readers focused on global trade and economy trends, Singapore's experimentation offers a glimpse of how finance might be embedded more deeply into supply chain data flows rather than operating on top of them. It also raises questions about data governance, cross-border privacy rules, and cyber-security, which regulators and industry bodies will need to address collaboratively.
Competitive landscape: other hubs and regional dynamics
Singapore is not the only Asian center competing to host regional supply chain finance operations. Hong Kong, Shanghai, and, increasingly, Dubai and other Gulf hubs all aspire to play significant roles in trade and working capital finance. Each offers its own mix of advantages, from proximity to mainland China to connections with Middle Eastern and African markets.
Singapore's differentiation lies in its focus on Southeast Asia, its legal and regulatory reputation, and its early move into digital trade infrastructure. The presence of international organizations, regional headquarters of multinationals, and a dense network of professional services firms-law, accounting, logistics, and consulting-reinforces its status as a coordination hub rather than a single-market center.
In the medium term, competition is likely to intensify as other jurisdictions adopt MLETR-style reforms, invest in trade platforms, and court fintechs. For corporates and financiers, this could be beneficial, driving interoperability and innovation across multiple hubs. Singapore's challenge will be to maintain its lead in governance, connectivity, and talent while remaining open to cross-border collaboration rather than trying to build closed, proprietary systems.
What Singapore's role means for businesses and financiers
For businesses operating in or trading with Asia, Singapore's role in regional supply chain finance has several practical implications.
First, it offers a natural base for designing cross-border SCF programs that can reach suppliers across multiple markets while maintaining consistent governance and risk standards. Many global banks and trade platforms already treat Singapore as their primary Asian hub for such solutions.
Second, the city-state's digital trade initiatives and legal reforms around electronic documents can reduce friction and processing times for trade transactions, particularly when combined with e-invoicing and integrated logistics data. Firms that align their internal systems with these emerging standards may find it easier to access financing and negotiate better terms.
Third, Singapore's focus on SME inclusion and collaboration with multilateral institutions creates opportunities for mid-sized companies and smaller suppliers to tap into SCF structures anchored by larger buyers. This can support more resilient, diversified supply chains-an increasingly important goal in a world of geopolitical tensions and climate-related disruptions.
Finally, for investors and financial institutions, Singapore provides exposure to a growing asset class at the crossroads of stock exchange and capital markets, trade, and technology. Trade-linked receivables, SCF securitizations, and platform-based lending structures all draw on the city-state's financial infrastructure while channeling capital into the real economy across Asia.
As supply chains continue to evolve, Singapore's role will not be defined solely by its ports or airports, but by its ability to orchestrate the flow of information, risk, and capital that keeps regional trade moving. For now, it remains one of the most important vantage points from which to understand-and shape-the future of supply chain finance in Asia.
