The Expanding Role of Embedded Finance in a Converging Digital Economy
Embedded Finance as a Strategic Inflection Point
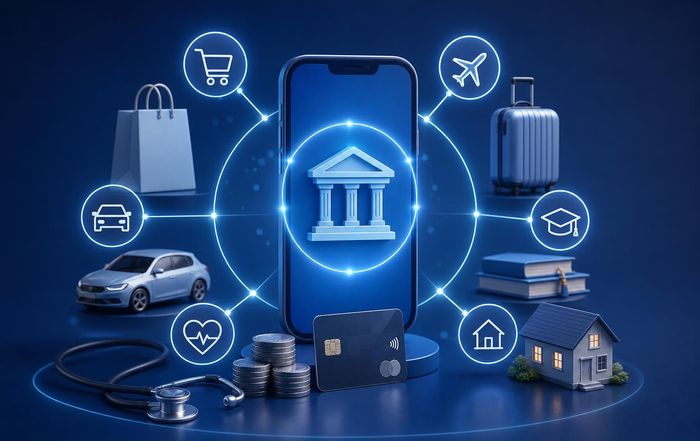
By 2026, embedded finance has moved from being a niche fintech concept to a decisive strategic lever for companies across sectors, reshaping how value is created, distributed, and monetized in the global economy. Rather than forcing customers to visit separate banking portals, payment gateways, or lending platforms, embedded finance integrates financial products directly into non-financial customer journeys, making financial interactions largely invisible, yet more powerful and data-driven than ever before. For the audience of TradeProfession.com, whose interests span artificial intelligence, banking, business, crypto, employment, innovation, investment, and technology, this shift is not a theoretical trend but a practical reality that is redefining competitive dynamics in the United States, Europe, Asia, and beyond.
At its core, embedded finance allows retailers, software providers, logistics platforms, and even manufacturers to offer services such as payments, credit, insurance, wealth management, and digital wallets within their own digital environments, often powered by banking-as-a-service infrastructures and open-banking APIs. As regulators in key markets such as the European Union, the United States, the United Kingdom, and leading Asian economies refine data-sharing and consumer-protection frameworks, embedded finance has evolved from early experiments into structured, scalable business models. Executives and founders who follow developments on business strategy and transformation now view embedded finance as a critical component of digital operating models, not an optional add-on.
From Payments to Platforms: The Evolution of Embedded Finance
The earliest and most visible manifestation of embedded finance emerged in digital payments, as platforms like Shopify, Uber, and major e-commerce marketplaces integrated frictionless payment options to reduce cart abandonment and increase conversion. Over time, these payment capabilities extended to include stored value, instant payouts, and multi-currency support, allowing platforms to behave increasingly like financial institutions without holding full banking licenses themselves. According to insights from McKinsey & Company, this transition from single-function payment tools to integrated financial ecosystems has created new profit pools, particularly in merchant acquiring, lending, and value-added services.
The evolution accelerated as open banking frameworks, such as those promoted by the UK's Open Banking Implementation Entity and the EU's PSD2 and PSD3 initiatives, made it easier for third-party providers to securely access bank data and initiate payments on behalf of customers. At the same time, cloud-native banking platforms and API-first fintechs enabled non-financial brands to plug in financial capabilities with far less complexity and capital expenditure than traditional banking integrations. Readers following technology and innovation trends will recognize embedded finance as part of a broader shift toward modular, composable digital architectures that allow organizations to assemble capabilities from specialized providers rather than building everything in-house.
Today, embedded finance has expanded beyond payments into lending, insurance, investment, and even payroll and benefits, turning many digital platforms into multi-service hubs. Industry analysis from Accenture and Deloitte highlights that the most advanced adopters are no longer experimenting at the edges but reconfiguring their business models around financial services as a core revenue stream and loyalty driver.
How Embedded Finance Creates New Business Models
For non-financial companies, embedded finance unlocks multiple pathways to growth, margin expansion, and differentiation. By integrating financial products directly into digital workflows, organizations can move from transactional relationships to ongoing financial partnerships with their customers, whether those customers are individuals, small businesses, or large enterprises. This shift aligns closely with the themes frequently explored on innovation and growth, where the convergence of data, technology, and new business models is reshaping entire industries.
One prominent example is the rise of embedded lending, including buy-now-pay-later (BNPL) and working-capital solutions for small and medium-sized enterprises. E-commerce platforms, enterprise resource planning providers, and B2B marketplaces can use transaction data and behavioral analytics to offer tailored credit at the point of need, often with faster decisioning than traditional banks. Research from the Bank for International Settlements and the World Bank underscores how such models can expand access to finance, especially in regions where small businesses historically struggled to obtain affordable credit from conventional lenders.
Similarly, embedded insurance has gained traction as mobility platforms, travel sites, healthcare providers, and consumer electronics brands integrate contextual coverage options directly into purchase flows. Rather than requiring customers to seek out a separate insurer, these services offer tailored policies-such as trip cancellation, device protection, or micro-insurance-precisely when customers are most likely to recognize their value. This approach not only boosts conversion but also deepens trust by making risk management an integral part of the customer experience.
Investment and wealth-building services are also being embedded into consumer and workplace platforms. Neobrokers and robo-advisers, many of which are covered in stock market and investment discussions, now power white-label investment features in payroll apps, digital banks, and even retail loyalty programs. Employees can direct a portion of their earnings into diversified portfolios without leaving their employer's platform, while consumers can round up purchases into investment accounts or crypto assets through embedded wealth tools, reflecting the growing intersection between traditional finance and digital assets.
The Regulatory Landscape Across Regions
The global regulatory environment has played a pivotal role in shaping the trajectory of embedded finance, with different jurisdictions adopting distinct approaches to open banking, platform accountability, and consumer protection. In the United States, regulators such as the Consumer Financial Protection Bureau (CFPB) and the Office of the Comptroller of the Currency (OCC) have focused on data rights, fair lending, and the responsibilities of banks that provide back-end services to fintechs. Developments in these areas can be followed through resources such as the CFPB website and the Federal Reserve, where guidance on digital payments, data access, and third-party risk management continues to evolve.
In Europe, the European Commission, European Banking Authority, and national regulators in countries such as Germany, France, and the Netherlands have advanced the most mature open banking frameworks, which are now extending into open finance and potentially open data more broadly. Interested readers can explore how these initiatives support competition and innovation through the European Commission's digital finance strategy. The United Kingdom, through the Financial Conduct Authority (FCA) and the Open Banking Implementation Entity, has been a global pioneer in creating standardized APIs and governance models that underpin many embedded finance solutions.
Across Asia-Pacific, regulators in Singapore, Australia, Japan, and South Korea are experimenting with open data regimes and digital banking licenses that encourage collaboration between incumbents and technology firms, while also paying close attention to financial stability and cybersecurity. The Monetary Authority of Singapore (MAS), accessible via its official portal, has become a reference point for progressive yet cautious regulatory frameworks that support embedded finance, digital assets, and cross-border payments. Meanwhile, in emerging markets across Africa, South America, and Southeast Asia, central banks and policymakers are examining how embedded finance can support financial inclusion, often in partnership with mobile network operators and super-app ecosystems.
For executives and policy watchers who rely on global economic and regulatory coverage, it is clear that embedded finance will continue to be shaped by a delicate balance between innovation and risk management. Regulatory clarity, particularly around data portability, liability allocation, and capital requirements, will determine how quickly and safely embedded finance scales across regions.
Data, AI, and the Personalization of Financial Services
Embedded finance is inseparable from the broader rise of data-driven personalization and artificial intelligence. Every time a consumer or business interacts with a platform-whether ordering food, booking transport, managing inventory, or paying employees-new data points are generated that can inform more precise financial decisioning. When combined with advances in machine learning and generative AI, these data streams enable real-time risk assessment, tailored product recommendations, and dynamic pricing, fundamentally changing how financial services are designed and delivered.
Organizations that follow developments in artificial intelligence and automation recognize that embedded finance represents one of the most commercially significant applications of AI in the financial sector. Credit models can be continuously updated to reflect current transaction patterns rather than relying solely on static credit scores, while fraud-detection systems can analyze behavioral cues across multiple platforms to flag anomalous activity. Leading technology firms such as Google Cloud, Microsoft Azure, and Amazon Web Services provide AI-enabled financial services components that non-financial brands can integrate into their offerings, often in partnership with regulated financial institutions.
Academic and industry research, accessible through sources like the MIT Digital Currency Initiative and the Stanford Digital Economy Lab, is exploring how AI-driven embedded finance can improve financial inclusion while also raising new ethical and governance questions. Bias in algorithms, explainability of credit decisions, and the potential for over-extension of consumer credit are all areas of intense scrutiny. For a business audience that values experience, expertise, authoritativeness, and trustworthiness, it is increasingly important to ensure that AI-powered embedded finance solutions are transparent, auditable, and aligned with emerging regulatory expectations on responsible AI.
Crypto, Digital Assets, and the Next Phase of Integration
While embedded finance initially emerged within the traditional banking and payments ecosystem, the rapid evolution of digital assets and tokenization is adding a new layer of complexity and opportunity. Stablecoins, central bank digital currencies (CBDCs), and tokenized securities are gradually being integrated into payment, remittance, and investment workflows, allowing platforms to offer faster settlement, programmable money, and access to new asset classes. Readers interested in the intersection of crypto, economy, and investment will recognize that embedded finance is becoming a bridge between conventional financial infrastructure and decentralized technologies.
Institutions such as the International Monetary Fund and the Financial Stability Board are closely monitoring these developments, evaluating how tokenized forms of money and assets might integrate with existing payment rails and banking systems. Embedded finance platforms may soon allow users to choose between traditional bank transfers, card payments, and on-chain settlement options, depending on cost, speed, and regulatory requirements. For cross-border commerce and remittances, this could significantly reduce friction and enable new forms of trade and financial inclusion, particularly in regions with underdeveloped correspondent banking networks.
At the same time, the integration of digital assets into embedded finance raises governance and compliance challenges, including anti-money laundering controls, sanctions screening, and consumer protection. Businesses that wish to incorporate crypto-enabled features into their embedded finance strategies will need to work closely with regulated custodians, compliance specialists, and legal advisors to ensure that innovation does not outpace risk management. The coverage of investment and financial innovation increasingly emphasizes that digital assets must be treated as part of a holistic financial architecture, not as isolated speculative instruments.
Implications for Employment, Skills, and Organizational Design
The expansion of embedded finance has significant implications for employment, workforce skills, and organizational structures across industries. As more companies adopt financial services as part of their core offerings, demand is rising for professionals who can bridge the domains of technology, regulation, risk, and customer experience. Product managers, data scientists, compliance officers, and engineers with embedded finance expertise are becoming highly sought after in markets from the United States and Canada to Germany, Singapore, and Australia.
For readers tracking employment and jobs trends, it is evident that embedded finance is contributing to the creation of new hybrid roles, such as platform risk architects, embedded finance partnership leads, and AI-enabled underwriting specialists. At the same time, traditional roles within banks, insurers, and payment providers are evolving, as these institutions increasingly position themselves as infrastructure providers and orchestrators rather than solely as direct-to-consumer brands. This shift requires new skills in ecosystem management, API productization, and data governance.
Education and professional development are adapting accordingly. Universities and business schools are launching specialized programs in fintech, digital banking, and platform economics, while executive education providers offer courses on embedded finance strategy, open banking, and regulatory technology. Those exploring education and upskilling resources will find that embedded finance is now a core topic within broader discussions of digital transformation and the future of work. Organizations that invest early in reskilling and cross-functional collaboration will be better positioned to capture the opportunities of embedded finance while managing its operational and compliance complexities.
Strategic Considerations for Executives and Founders
For executives, founders, and investors who form a substantial part of the TradeProfession.com community, the central question is no longer whether embedded finance will matter, but how to design and execute a strategy that aligns with their organization's capabilities, risk appetite, and market positioning. Leaders who regularly consult executive leadership insights are increasingly evaluating embedded finance through the lens of long-term competitive advantage rather than short-term revenue experiments.
Key strategic decisions include whether to act as a distributor of financial services, a balance-sheet provider, a technology enabler, or an orchestrator of a broader ecosystem. Non-financial brands must determine which financial products are genuinely value-accretive for their customers and how to structure partnerships with banks, fintechs, and infrastructure providers. Banks and insurers, in turn, must decide whether to compete directly with platform-based offerings or to embrace a white-label, embedded model that prioritizes scale and efficiency over brand visibility.
Marketing and customer-experience teams, drawing on perspectives from digital marketing and customer engagement, play a crucial role in ensuring that embedded finance offerings are positioned clearly and responsibly. Transparency around pricing, terms, and data usage is essential to building trust, especially as customers may not always realize they are engaging with financial products when using a platform. Clear communication and ethical design can differentiate providers in an environment where regulatory scrutiny and consumer expectations are steadily rising.
Risk, Resilience, and Trust in Embedded Finance
As embedded finance becomes more pervasive, questions of risk, resilience, and trust move to the forefront. The interdependence between non-financial platforms and regulated financial institutions creates complex chains of responsibility, where operational failures, cyber incidents, or compliance breaches in one part of the ecosystem can have cascading effects. Central banks and regulators, including those tracked by the Bank for International Settlements, are increasingly focused on third-party risk management, operational resilience, and the systemic implications of large technology platforms acting as critical financial infrastructure.
For businesses integrating embedded finance, robust risk management frameworks are indispensable. This includes clear contractual arrangements with partners, strong data-protection measures, regular stress testing of financial models, and contingency planning for service disruptions. Boards and senior management teams must treat embedded finance as a strategic risk domain, not merely a product extension, ensuring that governance structures reflect the heightened responsibilities associated with offering financial services.
Trust is equally critical from the customer perspective. Organizations that have built reputations in retail, logistics, travel, or software must recognize that entering financial services changes the nature of their relationship with customers, who will expect higher levels of reliability, clarity, and support. Platforms that succeed in embedded finance will be those that combine technical excellence with a deep commitment to customer outcomes, aligning with the broader emphasis on sustainable, responsible business practices promoted by bodies such as the OECD. For readers interested in sustainable and responsible business models, embedded finance offers both opportunities for positive impact and new responsibilities to manage financial well-being.
The Road Ahead: Embedded Finance as Infrastructure
Looking toward the late 2020s, embedded finance is poised to become an integral part of the digital infrastructure that underpins commerce, employment, and personal financial management worldwide. Just as cloud computing and mobile connectivity became invisible yet indispensable layers of the modern economy, embedded finance is likely to recede into the background of user interfaces while driving a growing share of revenue and value creation. For the global audience of TradeProfession.com, spanning North America, Europe, Asia, Africa, and South America, this transformation will shape how businesses scale, how individuals access financial services, and how policymakers think about competition and systemic risk.
The convergence of artificial intelligence, open data, digital assets, and embedded finance will create new possibilities for inclusive, efficient, and context-aware financial services, while also demanding higher standards of governance, security, and ethical design. Organizations that stay informed through reliable sources-whether central banks, international institutions, leading consultancies, or specialized platforms like TradeProfession.com-will be better equipped to navigate this evolving landscape.
Ultimately, the expanding role of embedded finance is not simply a technological phenomenon; it is a reconfiguration of the relationship between finance and the real economy. As platforms, banks, fintechs, and regulators continue to define their roles in this new architecture, the businesses that combine experience, expertise, authoritativeness, and trustworthiness will set the standard for how embedded finance delivers long-term value to customers, investors, and societies worldwide.
