Optimizing the Cash Conversion Cycle in Wholesale Trade
In wholesale trade, profitability often depends less on headline margins and more on how quickly cash moves through the business. A wholesaler can be growing sales and even showing accounting profits while silently running out of cash. The cash conversion cycle (CCC) is the core metric that connects inventory, receivables, and payables into one picture of working capital efficiency. Understanding and optimizing this cycle has become even more important as interest rates, supply-chain volatility, and credit conditions have tightened across major markets.
This article examines how the CCC works in wholesale trade, why it behaves differently from other sectors, and what practical levers executives can use to shorten the cycle without damaging supplier and customer relationships. It also looks at how technology, data, and financing tools are reshaping working capital management for wholesalers globally.
What the Cash Conversion Cycle Measures - And Why It Matters More in Wholesale
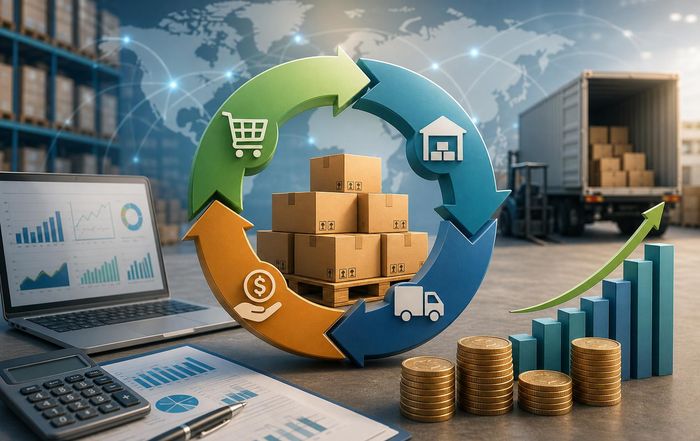
The cash conversion cycle measures how many days it takes for a company to convert its investments in inventory and receivables back into cash. In its standard form, the CCC is calculated as:
Days Inventory Outstanding (DIO)
plus Days Sales Outstanding (DSO)
minus Days Payables Outstanding (DPO)
For wholesalers, each component behaves differently from a retailer or manufacturer. Inventory positions are typically larger and more volatile than in retail because wholesalers must buffer demand for multiple downstream customers and often carry a broad SKU range. Receivables periods are longer because trade credit is a core commercial tool to win and retain customers. Payables may be constrained by supplier bargaining power, especially when dealing with large manufacturers or brand owners. The result is that many wholesale businesses run structurally longer cash cycles than other parts of the value chain, and small shifts in any component can have outsized cash impacts.
A shorter CCC generally means less cash is tied up in working capital, lower financing costs, and greater resilience in periods of demand shock or credit tightening. Institutions such as the World Bank and OECD have repeatedly highlighted how working capital efficiency strongly influences business survival, especially for small and medium-sized enterprises in trade sectors. In higher-rate environments, every additional day of CCC carries a real cost as overdrafts, trade finance, or term loans become more expensive. For executives and founders in wholesale, this makes CCC optimization not a back-office exercise but a central strategic lever for growth and risk management.
Readers looking for a broader view of how working capital interacts with macroeconomic conditions may find it useful to follow developments on global economic trends and banking and credit conditions, as these directly shape the cost and availability of trade finance.
How Wholesale Business Models Shape the Cash Conversion Cycle
Wholesale trade is not a single model. B2B distributors in industrial components, foodservice, pharmaceuticals, consumer electronics, construction materials, or apparel operate with very different inventory risks, margin structures, and bargaining positions. Those differences show up clearly in CCC patterns.
In sectors such as fast-moving consumer goods or pharmaceuticals, wholesalers often operate under tight service-level agreements that require high availability and rapid fulfillment. This pushes Days Inventory Outstanding higher, but that can be partly offset by strong relationships with large retailers or pharmacies that accept standardized payment terms and electronic invoicing, helping to keep DSO under control. In contrast, distributors of capital equipment or building materials may carry fewer SKUs but face highly cyclical demand and project-based sales, leading to lumpy receivables and more frequent disputes or delays in payment.
Regional factors also matter. In some European markets, legal frameworks around late payment and commercial credit terms, supported by organizations like the European Commission and national regulators, encourage shorter DSO and penalize excessive payment delays. In other jurisdictions, extended payment terms are culturally and commercially embedded, making it harder for wholesalers to accelerate collections without risking customer loss. International wholesalers must navigate this complexity while still managing working capital coherently across regions.
The growing role of e-commerce platforms and digital marketplaces has introduced new models where wholesalers sell directly to small businesses online, sometimes with card-based payments and instant settlement. This can dramatically reduce DSO but may require different inventory strategies and investment in digital infrastructure. Readers interested in how technology is reshaping distribution models may wish to explore broader coverage on technology in trade and innovation in business models.
Diagnosing Your Cash Conversion Cycle: From Metric to Management Tool
Many wholesalers track DIO, DSO, and DPO as accounting metrics but do not fully use them as operational management tools. The first step in optimization is to build a clear, segmented view of the CCC rather than relying on a single company-wide number. This typically involves analyzing DIO by product family or supplier, DSO by customer segment or geography, and DPO by vendor and category. Large distributors often discover that a small subset of SKUs or customers accounts for the majority of working capital consumption.
Benchmarking against industry peers can provide useful context. Data from sources such as S&P Global, Moody's, and consulting firms like McKinsey & Company and Boston Consulting Group offer sector-level working capital benchmarks, though care is needed to compare like with like in terms of business model and geography. Publicly listed distributors' financial statements can also be a rich source of comparative CCC data. However, internal benchmarking over time is usually more powerful: tracking how CCC responds to changes in pricing, terms, inventory policies, and supply conditions reveals which levers genuinely move the needle for a specific business.
It is also important to connect CCC metrics with operational KPIs and incentives. Sales teams driven purely by revenue or volume targets may extend generous payment terms or accept slow-paying customers without fully considering the cash impact. Procurement teams focused on purchase discounts may over-order to secure volume rebates, increasing DIO and offsetting any margin gains. Aligning incentives with working capital objectives-while monitoring customer satisfaction and service levels-helps ensure CCC optimization supports, rather than conflicts with, commercial strategy. For executives, this connects directly to broader business performance management and executive decision-making.
Reducing Days Inventory Outstanding: Balancing Availability and Cash
Inventory is often the largest working capital component for wholesalers, making Days Inventory Outstanding a primary optimization target. However, aggressive cuts to inventory can quickly backfire through stockouts, lost sales, and damaged customer relationships. The challenge is to reduce DIO while maintaining or improving service levels.
Improved demand forecasting is usually the starting point. Advances in data analytics and machine learning, supported by platforms from major technology providers such as Microsoft, Google, Amazon, and specialized supply-chain software vendors, allow wholesalers to forecast at a more granular level, account for seasonality, and respond to early signals of demand shifts. Integrating historical sales data with market indicators, promotional calendars, and macroeconomic variables can significantly reduce forecast error, which in turn enables lower safety stocks. When combined with tighter collaboration with key customers-sharing POS data or pipeline information-forecast accuracy can improve further, particularly in consumer and healthcare channels.
Segmentation of the product portfolio is another powerful tool. Applying ABC or more advanced multi-criteria segmentation helps identify which SKUs deserve high availability and which can be ordered less frequently or even moved to make-to-order or drop-ship arrangements. Long-tail products with low, erratic demand but high unit value often consume disproportionate working capital. Negotiating vendor-managed inventory or consignment arrangements for such items can shift inventory risk back up the supply chain, though this typically requires strong relationships and may affect purchase pricing. Here, insights from investment and capital allocation can help leaders weigh the trade-offs between cash, margin, and growth.
Operationally, shorter replenishment cycles, improved supplier lead-time reliability, and better warehouse management also support lower DIO. Efforts to consolidate warehouses or improve slotting and picking efficiency can reduce the need for duplicated safety stock across locations. Collaboration with logistics providers and use of real-time tracking technologies, supported by the broader digitalization of supply chains championed by organizations such as the World Economic Forum and International Chamber of Commerce, further enhances visibility and responsiveness.
Accelerating Collections: Managing Days Sales Outstanding Without Losing Customers
Days Sales Outstanding is heavily influenced by commercial strategy. In wholesale, trade credit is not simply a risk but a competitive tool. However, poorly controlled credit policies can quietly erode cash and increase bad-debt risk. Optimizing DSO means designing credit terms that support sales while being actively managed through risk assessment, monitoring, and collections processes.
A structured credit policy typically starts with segmenting customers by creditworthiness, size, and strategic importance. Credit ratings from agencies like Dun & Bradstreet or data from banking partners can support this process, but wholesalers should also rely on internal payment history and behavioral indicators. High-risk or new customers may be offered shorter terms, lower credit limits, or secure payment methods, while long-standing, reliable customers may benefit from more flexible arrangements. The goal is to avoid a one-size-fits-all credit approach that treats every account as equally safe.
Digitalization of invoicing and collections can materially reduce DSO. Electronic invoicing, automated dunning workflows, and online payment options reduce administrative delays and errors that often extend payment cycles. Many wholesalers have adopted customer portals where buyers can view invoices, dispute items, and make payments directly, reducing back-and-forth communication. Integration with enterprise resource planning (ERP) systems and treasury platforms enables real-time monitoring of overdue accounts and earlier intervention. These trends sit within a broader wave of technology-driven innovation in financial operations, with AI increasingly used to predict which invoices are at risk of late payment.
Incentives and penalties also play a role. Early-payment discounts can encourage faster settlement, though they must be evaluated against the cost of capital and margin impact. Late-payment fees can deter chronic delays, but their effectiveness varies by jurisdiction and relationship dynamics; in some markets, strong enforcement of such penalties is supported by legal frameworks, while in others it may be commercially difficult. Collaboration with banks and fintechs offering invoice financing, factoring, or dynamic discounting platforms can provide additional flexibility, allowing wholesalers to monetize receivables earlier while offering customers longer terms, though at a financing cost that needs to be carefully modeled.
Extending Days Payables Outstanding Responsibly
Days Payables Outstanding is sometimes seen as the easiest CCC lever: simply pay suppliers later. However, wholesalers that push payables too aggressively can damage supplier relationships, lose preferential pricing, or find themselves at the back of the queue during supply shortages. Optimization of DPO is therefore as much about negotiation and partnership as about unilateral policy changes.
Wholesalers with strong purchasing volumes often have more bargaining power and can negotiate extended standard terms, volume-based rebates, or structured payment plans. Transparent discussions with suppliers about cash needs, seasonality, and mutual growth objectives can lead to arrangements that benefit both sides, such as aligning payment dates with the wholesaler's own collection patterns. For example, where end-customers typically pay in 45 days, negotiating 60-day terms with suppliers can materially improve the cash cycle without creating undue strain.
Supply-chain finance solutions, often offered by large banks and specialized platforms such as SAP, Oracle, or independent fintechs, can also help. In these models, the wholesaler's stronger credit profile is used to enable early payment to suppliers by a financing institution, while the wholesaler settles later with the financier. This effectively increases DPO from the buyer's perspective while giving suppliers faster access to cash. However, the accounting treatment, fees, and potential impact on financial ratios need careful assessment, particularly for listed companies or those with bank covenants.
Ethical and reputational considerations are increasingly important. Regulators and industry bodies in several markets have criticized excessive payment delays to small suppliers, and some governments publish league tables of payment practices. Wholesalers that rely heavily on small or emerging suppliers must balance their own working capital needs against the financial health of their supply base. In some cases, paying smaller suppliers more quickly while negotiating longer terms with large, well-capitalized manufacturers may be a more sustainable approach, aligning with broader sustainability and responsible business considerations.
Integrating Technology, Data, and AI into Working Capital Management
The last decade has seen a rapid expansion of tools to manage CCC more dynamically. Modern ERP platforms from providers like SAP, Oracle, and Microsoft, alongside specialized working capital and treasury systems, allow wholesalers to monitor DIO, DSO, and DPO in near real time. Instead of relying on quarterly reports, finance and operations teams can see daily or weekly movements, drill down to root causes, and test scenarios.
Artificial intelligence and advanced analytics are increasingly used to forecast cash flows, predict late payments, and optimize inventory policies. Machine learning models can analyze historical customer behavior, macroeconomic variables, and order patterns to identify accounts likely to delay payments or default, allowing earlier engagement or adjustment of terms. Similar techniques can suggest optimal reorder points or safety stock levels by SKU, considering lead-time variability and demand volatility. Readers interested in the broader implications of AI for financial and operational decision-making may find additional context in coverage on AI applications in business.
Digital platforms have also changed how wholesalers access financing. Beyond traditional bank credit, fintech providers and alternative lenders offer invoice financing, dynamic discounting, and embedded finance solutions directly integrated into ERP or e-commerce systems. While organizations like the Bank for International Settlements and national regulators monitor these developments for systemic risk and consumer protection, for many wholesalers they provide additional flexibility in managing the CCC, particularly when bank lending conditions tighten.
However, technology is not a panacea. Poor data quality, fragmented systems, and lack of process discipline can undermine even the most sophisticated tools. Successful implementations typically combine technology investment with governance, clear ownership of working capital metrics, and cross-functional collaboration between finance, sales, procurement, and operations. This is where broader themes around employment and skills intersect with working capital: teams need analytical capabilities and change-management skills, not just transactional expertise.
Risk, Resilience, and Scenario Planning Around the Cash Conversion Cycle
Optimizing the CCC is not solely about minimizing it. A very lean cash cycle can leave wholesalers vulnerable to shocks. The pandemic-era supply disruptions, energy price spikes, and geopolitical tensions of recent years have highlighted the value of resilience. In some sectors, distributors that had previously pushed inventory levels to the minimum found themselves unable to fulfill orders when supply chains faltered, losing market share to competitors with more buffer stock.
Scenario planning is therefore essential. Finance and operations leaders should regularly test how the CCC would behave under different conditions: a sudden demand slump, a major supplier failure, a tightening of customer credit, or a sharp change in interest rates. Tools and guidance from institutions such as the International Monetary Fund, World Bank, and national central banks can help frame macroeconomic scenarios, while industry associations provide sector-specific risk insights. Stress-testing working capital under these scenarios allows wholesalers to define acceptable ranges for DIO, DSO, and DPO and to set contingency actions in advance.
Risk management also includes credit insurance and hedging strategies. Trade credit insurance, offered by major global insurers, can protect against large customer defaults and may enable more confident extension of terms. However, it comes at a cost and with policy conditions that need careful evaluation. Currency risk can also affect CCC in cross-border wholesale trade, as receivables and payables denominated in different currencies may move out of sync. Coordinating working capital management with treasury and risk functions ensures that CCC optimization does not inadvertently increase exposure elsewhere.
For founders and executives building or scaling wholesale businesses, integrating CCC thinking into strategic planning is crucial. Decisions about new markets, product lines, or channel strategies should include explicit analysis of working capital intensity and cash-cycle implications, not just revenue and margin projections. This connects directly with broader themes around global expansion and entrepreneurial strategy.
Building a Working Capital Culture in Wholesale Organizations
Sustainable CCC optimization depends on culture as much as on analytics. In many wholesalers, working capital is seen as the responsibility of the finance department, while sales, procurement, and operations focus on their own KPIs. Shifting to a culture where everyone understands the cash implications of their decisions can unlock significant improvements without major structural changes.
This often starts with education. Explaining the cash conversion cycle in clear, operational terms-how much cash is tied up in inventory, how many days of sales are outstanding, and what that means for investment capacity-helps teams connect their daily choices to the company's financial health. Sharing simple dashboards, running workshops, and including working capital metrics in regular performance reviews can reinforce this understanding. Internal communication that highlights successes, such as a reduction in DSO for a particular customer segment or a smarter inventory strategy for a product line, builds momentum.
Incentive structures also play a crucial role. Compensation schemes that reward sales growth without regard to cash effects can encourage extended payment terms or overstocking to hit volume targets. Adjusting bonuses to include metrics like DSO, inventory turns, or overall CCC, alongside revenue and margin, encourages more balanced decision-making. Some wholesalers implement cross-functional targets where teams share responsibility for working capital outcomes, fostering collaboration between finance, sales, and operations.
Finally, governance matters. Regular working capital reviews at executive level, clear accountability for CCC components, and integration of cash metrics into board reporting signal that the cash conversion cycle is a strategic priority, not an afterthought. As global conditions evolve and competition intensifies, wholesalers that treat CCC optimization as an ongoing management discipline, rather than a one-off project, are likely to be better positioned to invest, adapt, and grow.
By approaching the cash conversion cycle as a strategic, cross-functional discipline-supported by data, technology, and thoughtful stakeholder management-wholesale businesses can free up significant cash, reduce financing dependence, and build resilience against economic and supply-chain shocks. For many distributors, the most accessible source of growth capital is not a new loan or investor, but the cash already trapped in their own inventory, receivables, and payables.
